Don’t Go to College or Buy a House… If You Want Freedom & Money
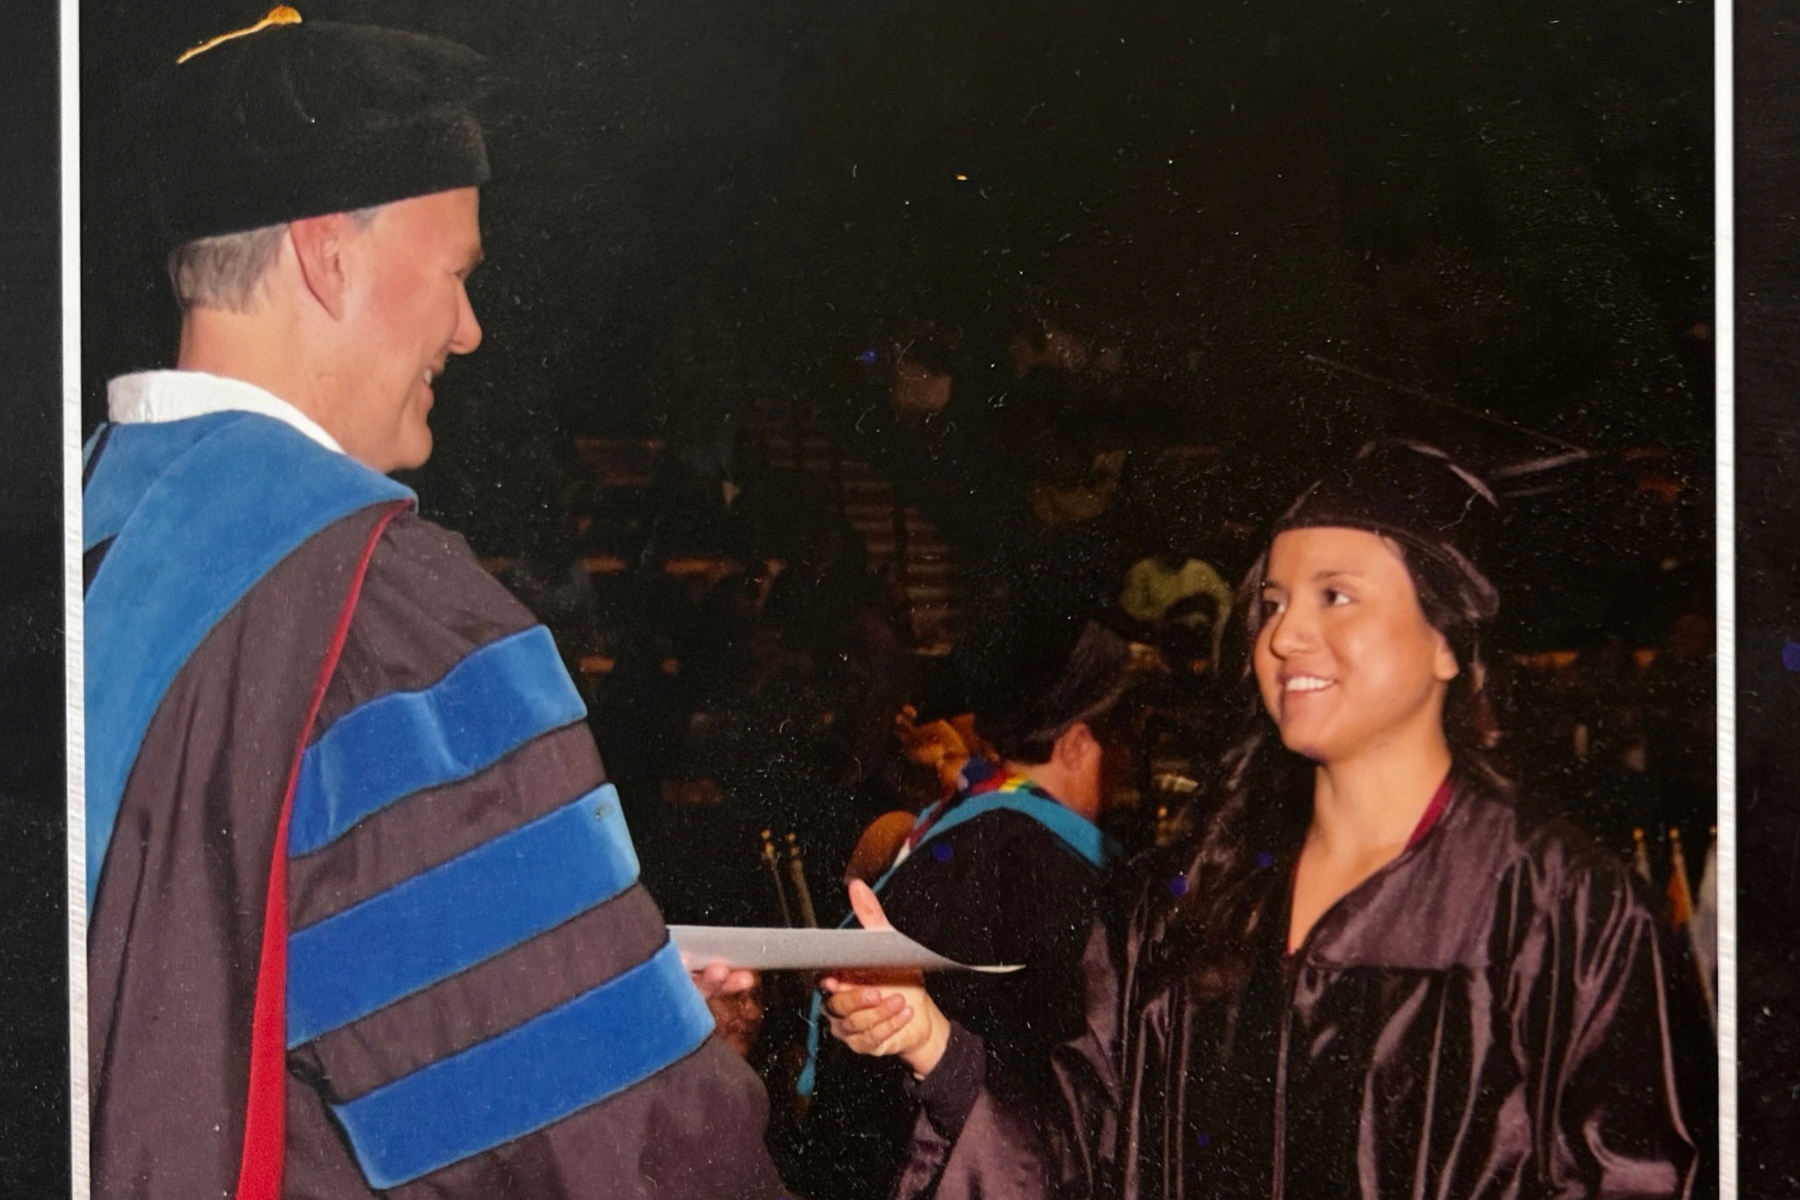
Plot twist: I went to college.
We’re taught a pretty specific formula for a successful life:
Go to college. Get a good job. Buy a house. Work for the next 30 or 40 years. Pay off the mortgage. Retire.
For a long time, I didn’t really question that formula. It was simply what you were supposed to do.
But lately, I’ve been asking a different question:
What if some of the things we’re told will make us successful are actually costing us the very things we want most - our money, time, and freedom?
I’m not saying no one should go to college. And I’m certainly not saying no one should buy a house.
I’m saying we should stop doing these things automatically.
Before taking on tens or hundreds of thousands of dollars in financial obligations, maybe we should first decide what kind of life we actually want.
So, Is College Worth It?
College can absolutely be worth it when your chosen career requires a degree or when the financial and personal return justifies the cost. But it shouldn’t automatically be the right path for everyone.
Certifications, apprenticeships, professional licenses, entrepreneurship, community college, and entering the workforce earlier can offer alternative paths—sometimes with significantly less debt.
The better question might not be “Should I go to college?” but “Is college the best path to the life I actually want?”
Watch the Video
Prefer to watch? In the video below, I break down the numbers behind college debt, a 30-year mortgage, investing the difference, and why I started questioning the traditional path.
What if $40,000 bought freedom instead of debt?
I recently took a walk around a university campus and found myself wondering: Why are so many people still automatically going to college?
There are careers that absolutely require degrees. But there are also skills we can learn online, through certifications, apprenticeships, entry-level jobs, mentors, or simply by doing the work.
What fascinates me isn't only the cost of college. It's the difference between owing $40,000 and having $40,000.
Imagine finishing those four or five years with money in the bank instead of debt.
If your basic expenses were $1,300 per month, $40,000 could theoretically cover more than two and a half years of expenses with no income at all. In reality, you could work part-time, freelance, pick up a side hustle, learn a new skill, or build a business along the way.
Suddenly, that $40,000 isn't just money.
It's time. It's options. It's freedom.
Money could give you the ability to leave a toxic workplace, change careers, work fewer hours, start a business, or simply figure out what you want to do next.
That's why I've started looking at money differently.
I don't necessarily want more money so I can buy more things.
I want money because of the freedom it can create.
Is Buying a House Always a Good Investment?
Then there's the house.
“Buy a house.”
It's another piece of advice we're given almost automatically.
And homeownership can absolutely be a wonderful decision. You can put down roots, create stability, build equity and eventually own an asset outright.
But that doesn't mean it's right for everyone.
When we talk about buying a house, we tend to focus on the purchase price and monthly mortgage payment.
But there's also mortgage interest, maintenance, insurance, taxes, repairs and potentially PMI. And perhaps even more importantly, there's the responsibility of making that payment month after month.
A mortgage can provide stability.
But it can also reduce flexibility.
If your biggest priorities are putting down roots and creating a permanent home, that tradeoff might be completely worthwhile.
But if your priorities are flexibility, changing careers, starting a business, traveling, or simply needing less money to live?
Maybe it's worth running the numbers first.
What if You Invested the Difference?
This is where the conversation becomes more interesting.
What would happen if, instead of continually increasing our lifestyles as our incomes rise, we kept our expenses relatively low and invested the difference?
There's an important caveat here: choosing the cheaper option doesn't automatically make you wealthier.
If you rent for less than it would cost to own a home and then spend every dollar you saved, you haven't accomplished the same thing.
You have to actually save and invest the difference. That's the discipline behind the alternative you're choosing.
That's the philosophy I've become increasingly interested in:
Live below your means. Save the difference. Invest the difference. Use the freedom that creates to build the life you actually want.
Alternatives to College: What I Wish I Had Considered
This isn't just theoretical for me.
I went to college.
And looking back, I sometimes wish I had taken a different path.
I wonder what would have happened if I had spent four or five years developing a license or marketable skill, earning money, living like I was broke, and saving and investing as much as I possibly could.
Instead of spending those years paying a university, what if I had finished them with tens of thousands of dollars saved?
What could I have done with that money?
Invested it. Started a business. Changed careers. Bought myself time to figure out what I really wanted.
That's the part I wish I had understood earlier:
There wasn't only one path available to me.
The Traditional Path Wasn’t Working for Me
Eventually, I started questioning the standard advice I had spent years following.
I had gotten into debt. I had to climb my way out of it. And eventually I reached a point where I could finally stop reacting to life and start asking myself:
What do I actually want?
Years ago, I decided that the traditional plan wasn't working for me.
So I started living like I was broke.
I saved the difference.
I invested the difference.
And slowly, that gave me something I value more than having more stuff:
the ability to pivot.
The ability to think about changing careers. To build something. To decide what's next instead of automatically doing whatever I'm “supposed” to do next.
What Do You Actually Want?
That's why this conversation isn't really about college.
And it isn't really about houses.
It's about something much bigger:
Who defined success for you?
Maybe your version of success really is a college degree, a great career, a beautiful house and a family.
There's nothing wrong with that.
But maybe success looks like living in a small apartment with low expenses and having afternoons free.
Maybe it's starting a business.
Maybe it's creating art.
Maybe it's spending more time outside.
Maybe it's having enough money saved that you never feel trapped in a workplace you hate.
The point isn't to reject the traditional path simply because it's traditional.
The point is to consciously choose your path.
Toward the end of the video, I talk about the idea of reaching the end of your life and realizing you lived according to other people's expectations rather than your own. That's what I don't want—for myself or for anyone reading this.
Define Success for Yourself
Companies have mission statements.
They have core values.
We're even told to research those things before interviewing for a job.
But here's a question I've been thinking about:
What's your mission?
What are your core values?
What do you actually want your life to look like?
And what are you willing—or unwilling—to give up to create it?
Maybe the traditional path is right for you.
Maybe it isn't.
But either way, it should be your decision.
Frequently Asked Questions
Is college worth it?
College can be worth the investment when your career requires a degree or the expected financial and personal benefits justify the cost. The important thing is to compare the cost with realistic alternatives rather than assuming college is automatically the best option.
What are alternatives to college?
Alternatives can include trade schools, professional licenses, certifications, apprenticeships, entrepreneurship, community college, entry-level work, and learning marketable skills independently.
Is buying a house always better than renting?
No. Homeownership can provide stability and equity, but it also comes with mortgage interest, taxes, insurance, maintenance and reduced flexibility. Renting can make more sense depending on your finances, location and lifestyle goals.
How can living below your means create more freedom?
Spending less than you earn creates money that can be saved or invested. Over time, those savings can give you more flexibility to change careers, leave an unhealthy job, start a business or work less.